
Tariff Financial Impact & Forecasting Guide (2026) | Procurement and Tariff Intelligence
Quick Answer: How Does Tariff Financial Impact Modeling Work?
Tariff financial impact modeling quantifies how tariff rate changes affect landed cost, gross margin, EBITDA, and operating budgets using structured frameworks that connect HS classification data to financial forecasts. Organizations start with product-level import data mapped to HS codes, apply tariff rates (including stacking), calculate cost impact by supplier and category, then model scenarios for rate increases, supplier shifts, and trade policy changes. The result is an executive-ready report that shows tariff exposure by product, supplier, and trade action — not just a single total-dollar figure.
Effective tariff forecasting requires precision at the HS code level rather than category estimates, because tariff rates and policy overlays vary significantly by classification. Organizations that model quarterly and update for policy changes make faster sourcing decisions when tariff conditions shift.
Who This Guide Is For
This guide is designed for CFOs and finance directors modeling tariff cost exposure and its impact on operating forecasts, procurement leaders preparing executive-level tariff impact reports, supply chain VPs evaluating how sourcing cost changes affect supplier contracts and margins, FP&A analysts building tariff scenario models for board reporting, and controllers managing duty expense accruals and tariff-related balance sheet impacts.
Key Takeaways
- Tariff impact is not a single number — it varies by product, supplier, country of origin, and trade policy overlay combination, requiring HS-code-level analysis rather than portfolio-level estimates.
- EBITDA sensitivity to tariff changes depends on import concentration, margin structure, and the organization’s ability to pass costs through to customers or absorb them internally.
- Effective tariff forecasting requires HS-code-level data mapped to actual invoice volumes, not product-category estimates or historical averages that mask critical cost concentration.
- The tariff stacking effect (MFN base + Section 301 + Section 232 + Section 122) means effective rates on some product lines exceed 40%, creating margin pressure that simple tariff overlays underestimate.
- Executive-ready tariff reports must show exposure by supplier, product category, and trade action — not just a total dollar figure — to enable decision-making on sourcing strategy and pricing.
- Organizations that model tariff scenarios quarterly (rate increases, supplier shifts, program changes) make faster sourcing decisions when policy changes occur, gaining competitive advantage over companies that forecast only annually.
Tariff financial impact modeling has become a core procurement and finance discipline for 2026. Organizations import products that face MFN base rates, Section 301 overlays, Section 232 (steel/aluminum) rates, Section 122 universal baseline tariffs, and a growing web of trade policy layers. Each policy carries different rate structures, affected product classifications, and policy uncertainty. For CFOs, procurement directors, and FP&A teams, the challenge is not just knowing tariff rates — it is modeling how those rates flow through to cost of goods sold, gross margin, EBITDA, and ultimately to financial forecasts that the board relies on.
Many organizations still treat tariffs as a fixed cost adjustment applied at the portfolio level. This approach masks the actual cost concentration, underestimates true exposure in high-tariff product categories, and produces forecasts that diverge from reality when sourcing or trade policy shifts occur. This guide provides the structured frameworks, step-by-step modeling process, and executive reporting patterns that finance teams use to build tariff exposure models that are both precise and actionable.
Why Tariff Financial Impact Modeling Matters in 2026
Tariff policy has become a permanent fixture of U.S. trade rather than a temporary disruption. The current policy landscape includes Section 301 tariffs on China (25% on $200+ billion in annual imports), Section 232 tariffs on steel and aluminum, Section 122 universal baseline tariffs, and ongoing policy uncertainty around tariff escalation, product coverage changes, and exclusion decisions. For CFOs, this creates a dual challenge: understanding the current tariff cost impact on operating results, and forecasting how tariff changes will affect future margins and competitiveness.
Organizations that model tariff impact only at year-end, or that use portfolio-level averages to estimate cost impact, consistently underestimate exposure in specific product categories and miss opportunities to adjust sourcing strategy before margin pressure becomes severe. Finance teams that build HS-code-level tariff models, update them when policy changes, and run scenario analyses generate forecasts that are 15-30% more accurate than category-level estimates. This precision translates to better board reporting, more confident guidance, and faster response when trade policy shifts.
Three Reasons Financial Teams Must Model Tariff Impact Precisely
1. Tariff exposure is not distributed evenly across the product portfolio. A manufacturing company sourcing 80% of imported content from non-tariff countries but 20% from China faces radically different tariff costs than a company with inverted percentages. Portfolio-level averages hide this concentration. HS-code-level analysis reveals which supplier relationships and product lines are creating disproportionate tariff burden.
2. Tariff rates vary dramatically by classification and stacking. A product with a 3% MFN base rate faces a 28% effective tariff if Section 301 (25%) applies. Another similar product with a 12% MFN rate and Section 301 faces 37%. A third product with the same MFN but subject to Section 232 (25%) and Section 122 (10%) faces 47%. The difference in effective rate produces radically different margin impact, yet many organizations apply a single tariff “blended rate” to their entire China import portfolio.
3. Tariff costs flow directly to EBITDA and require operational response. Unlike many cost pressures that procurement can address over time, tariff costs hit immediately when goods clear customs. If a tariff-driven cost increase of 8-12% cannot be passed through to customers, it reduces gross margin by that amount. EBITDA sensitivity to tariff changes is not a footnote — it is a material forecast variable that CFOs must incorporate into quarterly earnings guidance and annual operating plans.
The Tariff Cost Structure — Understanding What Drives Financial Exposure
Tariff cost impact is a function of four interconnected components: the MFN (Most Favored Nation) base tariff rate, policy overlays that stack on top of the base rate, the volume and value of goods subject to each rate, and the organization’s ability to pass tariff costs through to customers or absorb them in margin. Understanding each component is essential for accurate financial modeling.

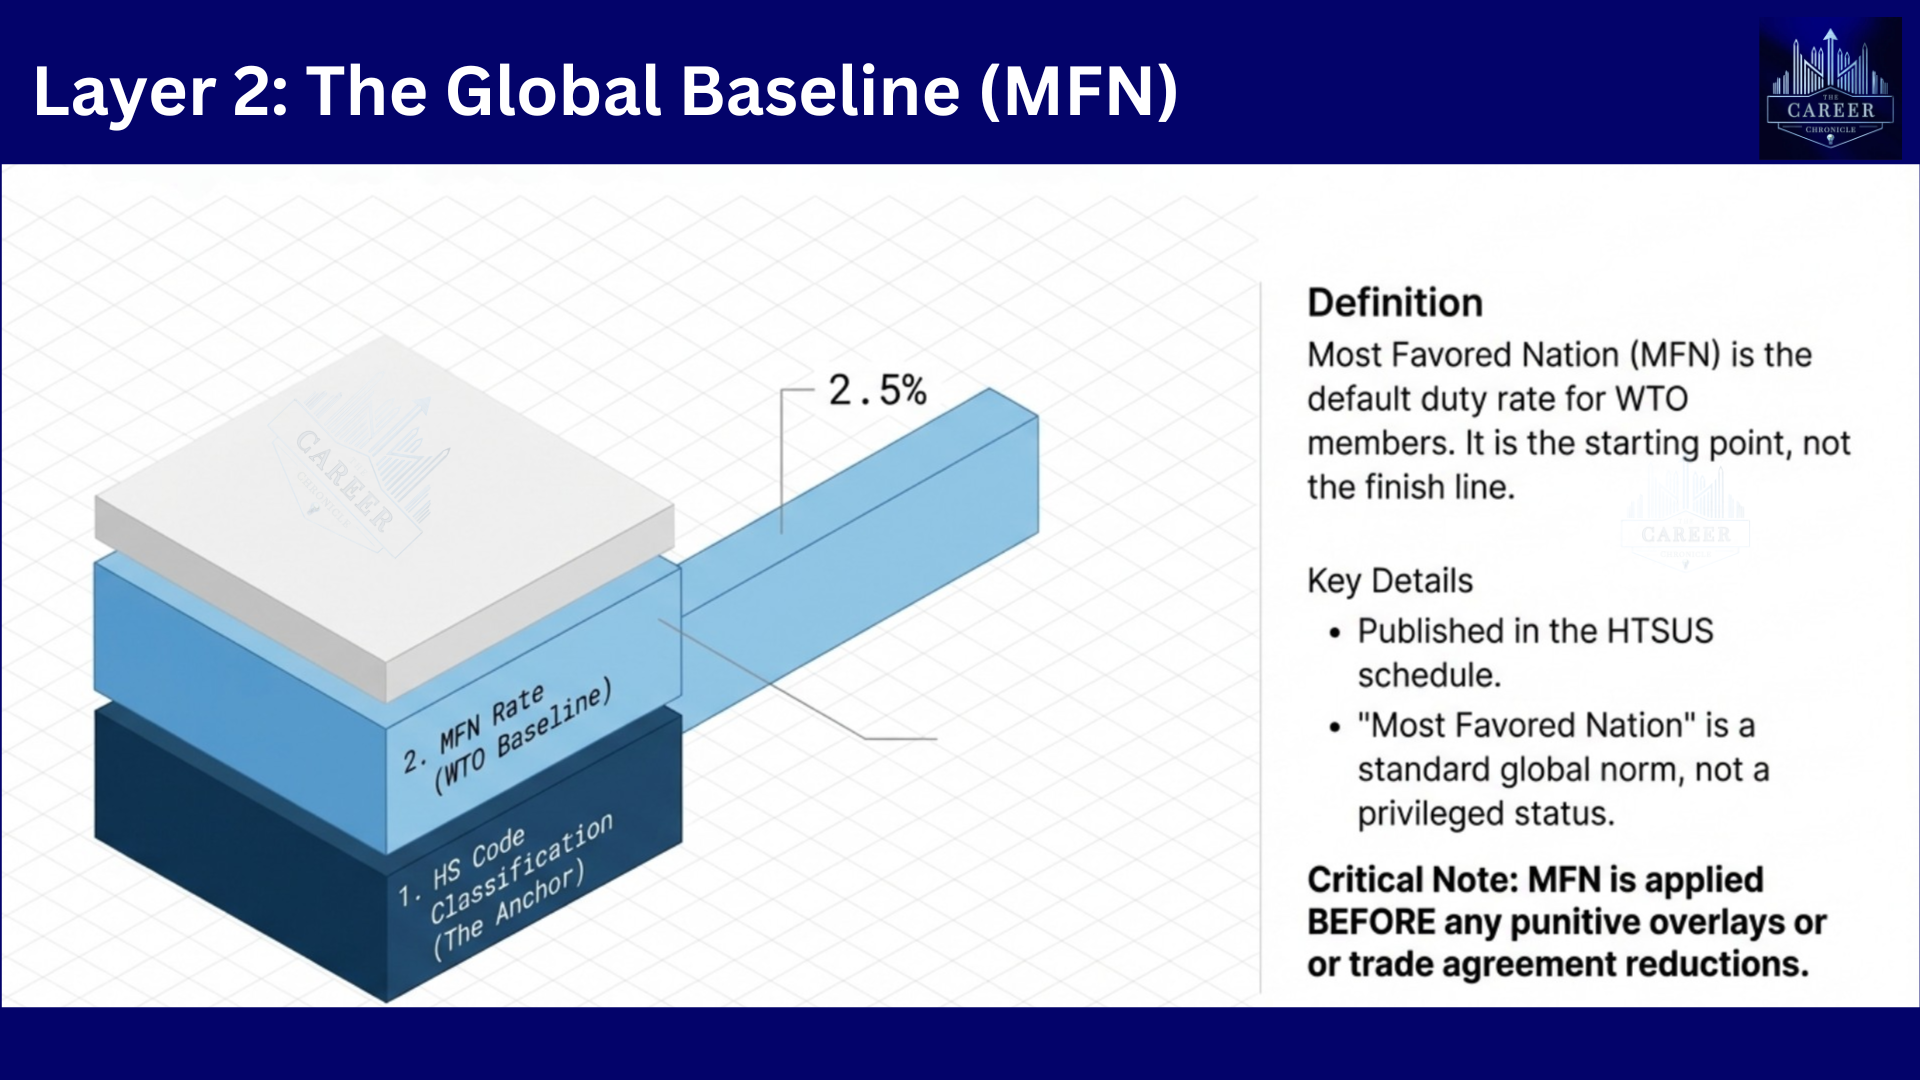
Component 1: MFN Base Rates
The MFN base rate is the foundational tariff that applies to imports from most countries. For U.S. imports, MFN rates are published in the Harmonized Tariff Schedule of the United States (HTSUS) and vary by 10-digit HS code. Base rates range from zero (many agricultural inputs, raw materials) to 30%+ (certain apparel, footwear, and agricultural products). Organizations often assume base rates are uniform across a product category, but tariff classifications are extraordinarily specific — one component rated as 8542.31.00 carries a different rate than 8542.39.00, even if both are semiconductors.
Component 2: Policy Overlays and Stacking
On top of the MFN base, multiple policy overlays can apply simultaneously. Section 301 adds 7.5% to 25% for Chinese imports. Section 232 adds 25% for steel and aluminum regardless of origin. Section 122 adds 7.5% to 10% for certain products. Preferential trade agreements (USMCA) can reduce or eliminate tariffs for products meeting rules of origin. The cumulative effect creates “stacking” where multiple policies apply. A product with a 5% MFN rate subject to both Section 301 (25%) and Section 232 (25%) faces a 55% effective tariff — a rate that transforms cost economics and often makes the sourcing decision untenable.
Component 3: Volume and Declared Value
Tariff cost in dollars is a function of the tariff rate applied to the customs value of imported goods. Customs value is the transaction price (invoice amount) plus certain adjustments. A product with a high per-unit cost sourced from an expensive supplier carries higher absolute tariff cost than a low-cost commodity. Organizations must model tariff by both rate (the percentage) and by value (the dollar amount of goods flowing through customs) to understand total exposure.
Component 4: Cost Pass-Through Economics
The financial impact of tariff costs depends on whether an organization can pass tariff cost increases through to customers. A company selling commodity-like products in a competitive market may have limited pricing power and must absorb tariff cost in margin. A company with differentiated products and strong customer relationships may negotiate price increases that recover tariff cost. A contract manufacturer may have contractual tariff pass-through provisions that shift tariff risk to the customer. Financial models must account for realistic cost pass-through assumptions, not assume all tariff costs are absorbable or all are recoverable.
The following table illustrates how tariff stacking affects effective rates. In practice, products often face multiple overlapping tariffs simultaneously.
| Product Example | MFN Base | Section 301 | Section 122 | Effective Rate | Tariff Cost on $100 Invoice |
|---|---|---|---|---|---|
| Laptop component from China | 2% | 25% | — | 27% | $27 |
| Stainless steel from China | 5% | 25% | 10% | 40% | $40 |
| Aluminum extrusion from China | 3% | 25% | 25% (232) | 53% | $53 |
| Furniture component from Vietnam | 8% | — | 10% | 18% | $18 |
| Auto part from Mexico (USMCA) | 0% (qualified) | — | — | 0% | $0 |
This table demonstrates the critical insight: identical suppliers and similar products can carry radically different tariff costs depending on the specific HS classification and applicable policy overlays. A portfolio-level average tariff rate masks this variation and produces forecasts that fail when sourcing decisions or policy changes occur.
How to Build a Tariff Financial Impact Model
Tariff financial impact modeling follows a seven-step process: data collection, HS code classification, tariff rate mapping, policy overlay stacking, volume and value multiplication, scenario modeling, and executive reporting. Each step is critical, and shortcuts in early steps undermine the accuracy of the final financial forecast.
Step 1: Import Data Collection and Preparation
Begin with 12 months of actual import data from customs records or procurement system records. The data should include invoice amount, quantity, unit of measure, HS classification (as declared to CBP), country of origin, supplier name, and product description. If your organization does not have a single system for this data, compile it from customs entry documents, trade compliance records, and AP/procurement systems. Clean the data to remove duplicates and correct obvious errors (misclassified entries, typos in country of origin codes).
For organizations with thousands of SKUs, this step often reveals that tariff classifications vary by supplier even for identical products, or that the same product is classified differently across different import shipments. Standardizing classification across suppliers is a prerequisite for accurate modeling.
Step 2: HS Code Mapping and Validation
Verify that the HS codes in your import records are correct to the 10-digit level. A product classified as 8542.31.00 (Semiconductor devices) carries a different tariff rate than 8542.39.00 (Other semiconductor devices). The difference matters because tariff rates are specific to the 10-digit code. Work with trade compliance or a customs broker to validate that your current classifications are defensible and that you are not over- or under-classifying products in ways that create tariff risk.
For products that may be susceptible to reclassification (tariff engineering opportunity), flag these separately. A product reclassification that moves it out of Section 301 coverage could reduce tariff cost by 25% without changing the sourcing location.
Step 3: Tariff Rate Mapping and MFN Base Rate Assignment
For each HS code in your portfolio, cross-reference the MFN base tariff rate from the HTSUS. Create a lookup table that maps your HS codes to their base rates. For organizations with 500+ SKUs, automated lookup tools that interface with tariff databases are more efficient than manual lookups. The goal is a spreadsheet or database with columns for product code, HS code, MFN base rate, product description, and primary sourcing country.

Step 4: Policy Overlay Stacking — Adding Section 301, 232, 122, and Other Overlays
For each HS code and country of origin combination, determine which policy overlays apply. If the product is sourced from China, check whether the HS code appears on any of the four Section 301 tariff lists. If the product is steel or aluminum (HS codes 7208-7326 for steel, 7601-7616 for aluminum), check Section 232 applicability. For Section 122 universal baseline (which began in 2024), identify which HS codes are covered. Add these overlay rates to the MFN base to calculate the total effective tariff rate.
This is where the tariff stacking problem becomes visible. A product with a 5% MFN base that hits multiple overlays jumps to 35-55% effective rate. Organizations often discover during this step that their China-sourced product concentration combined with tariff stacking creates far greater margin pressure than they expected.
Step 5: Volume and Value Multiplication
For each product (or HS code grouping), multiply the effective tariff rate by the volume and value of goods imported during your base year (typically the most recent 12 months). The result is the tariff cost in dollars. For example, if you imported $2 million of products subject to a 25% tariff, the tariff cost is $500,000. Aggregate across your full product portfolio to calculate total tariff exposure.
The key insight at this step is that tariff cost concentration usually mirrors import value concentration. 20% of your suppliers often account for 80% of import value and often face higher tariff rates than your low-volume suppliers. This concentration is critical for procurement response strategies (supplier diversification, sourcing optimization) and for board-level executive communication.
Step 6: Scenario Modeling — Rate Changes, Supplier Shifts, Program Variations
Once you have a baseline tariff cost model, run scenarios for credible policy and sourcing changes. Common scenarios include:
- Rate increase scenarios: What if Section 301 rates increase from 25% to 30%? What if Section 122 rates increase? Model both the cost impact and the EBITDA impact.
- Supplier shift scenarios: What if 25% of China volume shifts to Vietnam? What if a key supplier faces supply disruption and volume must move temporarily to a non-preferred sourcing location?
- Trade program expiration scenarios: What if USMCA tariff benefits expire? What if GSP (Generalized System of Preferences) eligibility for certain countries is rescinded?
- Reclassification scenarios: What if specific products qualify for alternative HS classifications that carry lower rates or avoid Section 301 coverage?
Scenario modeling reveals which sourcing decisions, rate changes, and trade policy shifts will have the greatest financial impact. Use scenarios to build range estimates for financial forecasts (“tariff cost will be $1.2 to $1.8 million depending on policy developments”) rather than point estimates.
Step 7: Aggregation and Executive Reporting
Aggregate the model outputs into a format ready for board reporting and executive decision-making. Total tariff cost by supplier, by product category, by trade action, and by country of origin. Calculate what percentage of total COGS tariff costs represent. Show the sensitivity of EBITDA to tariff rate changes in basis points. Compare scenarios to baseline to show decision impact.
Tariff Financial Modeling Workflow
EBITDA Sensitivity Analysis for Tariff Exposure
The ultimate goal of tariff financial impact modeling is understanding how tariff costs affect operating margin and EBITDA. This requires translating tariff costs (in dollars) into EBITDA impact (in margin percentage and basis points). The calculation depends on cost of goods sold, gross margin, and the organization’s ability to pass costs through to customers.
How Tariff Costs Flow to EBITDA
Tariff costs add directly to cost of goods sold. A tariff cost of $500,000 increases COGS by $500,000. The impact on gross margin percentage depends on total COGS and revenue. If a company has $100 million in COGS and applies a $500,000 tariff cost increase, COGS increases by 0.5% ($500,000 / $100 million). If gross margin is currently 35%, this tariff cost increase reduces margin to 34.5%. If operating leverage is 5x at the EBITDA line, this 0.5% margin reduction translates to approximately 2.5% EBITDA reduction.
Organizations with higher import concentration, lower cost pass-through ability, or thinner operating margins face amplified EBITDA sensitivity to tariff changes. A company with 60% of COGS from imports faces 1.5x greater tariff impact than a company with 40% import concentration, all else equal.
Building a Tariff-to-EBITDA Bridge
Create a waterfall analysis that shows how tariff cost changes flow through to EBITDA impact. Start with tariff cost in dollars, convert to COGS percentage, calculate gross margin impact, apply realistic cost pass-through assumptions (70% pass-through, 30% absorbed), calculate net margin impact, and apply EBITDA sensitivity multipliers. The result is an executive-ready view of tariff cost sensitivity in basis points of EBITDA.
Example for a $50M COGS operation with 40% gross margin and 5x operating leverage:
- Baseline tariff cost: $2.0M (4% of COGS)
- Gross margin impact: 160 basis points (2.0M / 50M × 100 × 0.8 where 0.8 = 80% of margin is subject to operating leverage)
- EBITDA impact: 50 basis points (160 × 5x × percentage of COGS tied to tariff-exposed imports)
- Sensitivity: 10 basis point EBITDA impact per 1% tariff rate increase on exposed products
Tariff Sensitivity Scenarios for Board Reporting
Create a sensitivity matrix showing EBITDA impact for different tariff rate scenarios. Show the impact on net income and EPS if tariff rates increase or decrease. This analysis is critical for guidance and for explaining earnings volatility driven by tariff policy changes that may be outside management’s control.
Tariff Scenario Modeling — Forecasting Before Policy Changes Hit
Effective tariff response begins with scenario modeling. Organizations that can forecast how policy changes will affect costs before tariff rate announcements take effect have time to adjust sourcing, negotiate contracts, and communicate with customers. Organizations that wait until tariffs are implemented to model impact are perpetually reactive.
Building Quarterly Tariff Scenario Models
Establish a quarterly process where finance and procurement teams review tariff policy landscape, identify credible risk scenarios, and model financial impact. The process involves:
1. Policy monitoring. Track USTR activities, trade negotiation developments, and policy announcements. Identify which policy changes would create greatest impact on your product portfolio.
2. Scenario identification. For identified policy risks, define specific scenarios. “Section 301 rates increase from 25% to 30%” or “Additional HS codes added to Section 301 Lists 3 and 4A covering consumer electronics.” Include low-probability but high-impact scenarios in addition to base-case policy assumptions.
3. Model updates. Update your tariff cost model with scenario assumptions. Recalculate total tariff exposure, gross margin impact, and EBITDA sensitivity under each scenario.
4. Decision support and option identification. For each scenario, identify what sourcing or operational decisions would mitigate cost impact. Model the cost, timeline, and risk of each mitigation option. Procurement teams use this analysis to prioritize supplier diversification projects or tariff engineering studies.
Using Scenario Analysis for Guidance and Planning
When communicating to the board and external stakeholders about tariff impact and outlook, use scenario ranges rather than point estimates. Example: “Based on current policy, we forecast tariff costs of $1.2-$1.8 million in 2026, with upside risk if Section 301 rates increase and downside benefit if additional exclusions are granted.” This framing acknowledges policy uncertainty while showing that you have modeled impact across a reasonable range of outcomes.
Building Executive-Ready Tariff Exposure Reports
The final step in tariff financial impact modeling is distilling the analysis into reports that enable executive decision-making. Effective reports answer four questions: How much tariff cost exposure does the organization face? Where is exposure concentrated (by supplier, product, trade action)? What is the sensitivity to policy changes? What options exist to reduce exposure and what is the cost and timeline of each option?
Report Structure 1: Tariff Cost Concentration Analysis
Show total tariff costs aggregated by:
- By trade action: How much cost is driven by Section 301 versus Section 232 versus Section 122 versus MFN base rates?
- By supplier: Which suppliers contribute the largest absolute tariff costs?
- By product category: Which product lines face the highest tariff rate exposure?
- By country of origin: China vs Vietnam vs other countries — what is the tariff cost differential?
This breakdown reveals where tariff policy change would have the greatest impact and therefore where response strategies should be prioritized.
Report Structure 2: EBITDA Sensitivity and Margin Impact
Show how tariff cost translates to margin impact and EBITDA sensitivity. Quantify:
- Tariff cost as a percentage of COGS
- Gross margin impact in basis points
- Net EBITDA impact in basis points (after cost pass-through assumptions)
- Sensitivity: basis point EBITDA impact per 1% tariff rate change
This analysis helps finance teams communicate to boards and investors the materiality of tariff impact on operating results and guides the threshold for when mitigation strategies become cost-justified.
Report Structure 3: Policy Scenario Analysis
Show baseline costs and tariff exposure under three to five credible policy scenarios. Examples:
- Baseline (current policy continues): $1.2M tariff cost, 45 basis point EBITDA impact
- Escalation (Section 301 increases to 30%): $1.5M tariff cost, 57 basis point EBITDA impact
- Exclusion (10% of Section 301 products granted exclusions): $1.1M tariff cost, 41 basis point EBITDA impact
These scenarios help boards understand the range of potential outcomes and the financial materiality of policy uncertainty.
Report Structure 4: Response Options and Procurement Strategy
For each major source of tariff cost exposure, identify response options and model their cost, timeline, and risk. Options typically include supplier diversification, tariff engineering, trade program optimization, and refund recovery. Quantify:
- Cost savings potential if executed
- Implementation cost and timeline
- Execution risk (supply continuity, quality risk, contract negotiation risk)
- NPV and payback period for each option
This analysis guides procurement strategy and helps procurement teams justify investment in tariff response projects to the CFO.
Look Up Tariff Rates by HS Code — Free Tool
Need to verify MFN base rates, Section 301 coverage, Section 232 applicability, or calculate effective stacked tariff rates for your products? Use the Live U.S. Tariff Rate Lookup.
Covers MFN base rates, Section 301 (all four lists), Section 232, Section 122, USMCA, GSP, and 5+ additional trade programs. Supports 60+ countries, 905 unique tariff rate lines, and 9 different trade authorities. Updated March 2026.
Common Mistakes in Tariff Financial Modeling
Organizations building tariff financial impact models often make six critical mistakes that undermine forecast accuracy and produce models that diverge from reality when sourcing or policy changes occur.
Mistake 1: Using Portfolio Averages Instead of HS-Code-Level Data
Calculating a single “blended” tariff rate and applying it across an entire product portfolio hides cost concentration and produces forecasts that are typically 15-20% less accurate than HS-code-level models. A portfolio with 70% of volume in Section 301 products and 30% in non-tariff products cannot be accurately forecast using a 17.5% blended rate. The actual exposure is in the 70% that faces 25% rates, with margin implications that the average masks.
Mistake 2: Ignoring Tariff Stacking
Calculating Section 301 (25%) but failing to account for MFN base rates, Section 122, or other overlays underestimates true cost exposure. A 5% MFN + 25% Section 301 + 10% Section 122 product faces a 40% effective rate, not a 25% rate. Organizations that calculate tariff cost impact using only Section 301 rates often discover during execution that true tariff burden is 50-100% higher than forecast.
Mistake 3: Not Updating Models for Policy Changes
Building a tariff model once in January and not updating it until next year means the model diverges from reality as new tariff lists are published, exclusions expire, or trade programs change. Quarterly model updates aligned with policy announcement cycles keep forecasts current and enable rapid response when conditions shift.
Mistake 4: Treating Tariffs as Entirely Fixed Costs
Tariffs are often variable costs that flow directly to COGS and EBITDA. Treating them as fixed cost that doesn’t scale with volume, or ignoring the ability to pass tariff cost through to customers via contract provisions, overstates margin impact. Conversely, assuming all tariff costs can be passed through underestimates competitive risk if customer price sensitivity is high.
Mistake 5: Not Modeling Country-of-Origin Mix Accurately
Assuming all volume from a supplier originates from a single country, when in reality some portion may be sourced from alternative origins or subject to different trade programs, introduces classification errors into the model. Accurate modeling requires country of origin at the invoice/shipment level, not assumptions based on supplier name.
Mistake 6: Excluding Refund Recovery Opportunities from Financial Modeling
Organizations that paid Section 301 tariffs during exclusion-eligible periods, that have HS classification errors, or that qualify for retroactive trade program benefits may be eligible to recover overpaid duties through CBP protests. These refunds are not zero-cost — they require compliance resources and CBP documentation review — but they should be modeled as potential one-time gains that offset ongoing tariff cost exposure.
What This Means for Procurement and Finance Teams
Map your imported products to HS codes and tariff rates. Start with 12 months of actual import data. Classify to the 10-digit HS code level. Cross-reference against the HTSUS to verify base rates and policy overlay applicability. This foundational step is where accuracy begins.
Calculate stacked effective tariff rates, not single-overlay rates. For each product, apply MFN base + all applicable overlays (301, 232, 122, trade program benefits). Model the cumulative rate, not just the Section 301 surcharge. This reveals true cost concentration and margin pressure.
Build quarterly scenario models and communicate ranges, not point estimates. Given policy uncertainty, effective financial communication uses tariff cost ranges (“$1.2-$1.8M depending on policy developments”) and shows sensitivity to credible policy scenarios. This approach demonstrates rigor while acknowledging uncertainty.
Connect tariff models to procurement response strategy and supplier decisions. Tariff analysis should drive sourcing decisions: which suppliers to diversify, which products to reengineer, which trade programs to optimize. Track the cost, timeline, and risk of each response option in a structured procurement plan.
Use tariff forecasting to improve guidance accuracy and reduce earnings surprises. Organizations that build robust tariff models and update them quarterly produce earnings guidance that incorporates policy uncertainty range and therefore diverges less from actual results. This builds investor confidence and reduces guidance miss risk.
Tariff Impact Automation Suite
TIAS-199 is a procurement and finance intelligence system for building HS-code-level tariff cost models, forecasting EBITDA sensitivity, and connecting tariff analysis to sourcing strategy.
Explore TIAS-199 →Expert Insight
Financial teams that model tariff exposure at the HS code level rather than estimating at the category level produce forecasts that are typically 15-30% more accurate, according to procurement strategist Ramie Virk. The precision matters because tariff cost impact flows directly to EBITDA and influences board reporting, guidance accuracy, and investor confidence.
Organizations that wait until tariff policies are implemented to model impact are perpetually reactive. The companies that manage tariff exposure effectively are the ones that model quarterly under multiple policy scenarios, update their models when policy changes occur, and use scenario analysis to guide procurement response strategy. This approach turns tariff uncertainty from an earnings risk into a managed variable that procurement and finance can communicate confidently to boards and investors.
Frequently Asked Questions — Tariff Financial Impact Modeling
How do tariffs affect EBITDA?
Tariff costs add directly to cost of goods sold, which increases COGS and reduces gross margin. The impact on EBITDA depends on gross margin percentage, cost pass-through ability, and operating leverage. A company with 40% gross margin that faces a tariff cost increase equal to 1% of COGS will see EBITDA decline by approximately 40-50 basis points (assuming some limited cost pass-through). Organizations with thinner margins or higher import concentration face amplified EBITDA sensitivity to tariff changes.
What data is needed for tariff financial impact modeling?
Effective modeling requires 12 months of actual import data including invoice amount, quantity, HS classification (10-digit code), country of origin, supplier name, and product description. Additional data helpful for scenario modeling includes customer contracts (to understand cost pass-through flexibility), COGS by product category (to calculate margin sensitivity), and supplier contract terms (to identify tariff escalation or pass-through provisions).
How do you calculate the effective tariff rate with stacking?
Effective tariff rate with stacking equals MFN base rate + Section 301 rate (if applicable for that HS code and country of origin) + Section 232 rate (if steel or aluminum) + Section 122 rate (if applicable) — any trade program reductions (USMCA, GSP, etc.). The result is applied to the customs value of the imported goods to calculate total tariff cost in dollars. A product with 5% MFN base + 25% Section 301 + 10% Section 122 faces a 40% effective tariff. Customs value is typically the transaction price plus adjustments per CBP rules.
What is tariff scenario modeling?
Scenario modeling quantifies how credible changes to tariff rates, policy coverage, or sourcing locations would affect total tariff cost and EBITDA. Common scenarios include rate increases (what if Section 301 increases from 25% to 30%), policy coverage changes (what if additional HS codes are added to Section 301 Lists), supplier shifts (what if 25% of China volume moves to Vietnam), and trade program changes (what if USMCA benefits expire). Scenario modeling enables organizations to forecast impact before policy changes take effect and guide procurement response strategy.
How often should tariff financial models be updated?
Quarterly updates aligned with trade policy announcement cycles are the best practice. This cadence captures new tariff lists, policy modifications, exclusion announcements, and other changes that affect model accuracy. Annual-only updates mean the model diverges from reality for 9 months of the year and miss opportunities for timely response to policy changes. At minimum, models should be updated whenever significant tariff policy changes are announced.
What should an executive tariff exposure report include?
Effective executive reports answer four questions: (1) How much total tariff cost exposure? (2) Where is exposure concentrated (by supplier, product category, trade action, country)? (3) What is EBITDA sensitivity to tariff rate changes? (4) What response options exist and what is the cost, timeline, and risk of each? Reports should show tariff costs under baseline policy and under credible policy change scenarios. Cost pass-through assumptions should be stated explicitly. The report should guide procurement strategy and resource prioritization.
Can tariff costs be passed through to customers?
Tariff cost pass-through depends on customer contracts, market competition, and product differentiation. Commodity suppliers in competitive markets often have limited pricing power and must absorb tariff costs. Differentiated product suppliers or contract manufacturers may have contractual pass-through provisions that shift tariff risk to customers. Financial models should use realistic pass-through assumptions based on actual contract language and customer price sensitivity, not assume full recovery or full absorption across all customers.
What tools do finance teams use for tariff forecasting?
Effective tools combine tariff rate databases (HTSUS, trade program databases) with import data systems (customs records, procurement systems) and financial modeling platforms (Excel, BI tools, ERP systems). Leading organizations use automated HS code classification tools that reduce manual entry error, tariff intelligence platforms that track policy changes and maintain updated rate databases, and scenario modeling tools that enable rapid sensitivity analysis. The Tariff Impact Automation Suite (TIAS-199) integrates import data, tariff rates, and financial modeling to enable HS-code-level forecasting without manual spreadsheet maintenance.
Links and References
- Tariff Impact Automation Suite (TIAS-199) — CareerChronicles.org
- Tariff Playbook Suite (SKB-027) — CareerChronicles.org
- Tariff Auto-Fill Tool (TAF-097) — CareerChronicles.org
- Live U.S. Tariff Rate Lookup — Free Tool
- Tariff Refund Suite (TRS-197) — CareerChronicles.org
- Tariff Scenario Strategy Kit — CareerChronicles.org
- HTSUS Official Schedule — U.S. International Trade Commission
Editorial Note
This article is published for informational and educational purposes. Career Chronicles products are referenced as examples of tariff intelligence tools within the broader discussion. Tariff rates, trade policies, HS classifications, and policy overlays change frequently. Always verify official HTSUS rates at hts.usitc.gov and consult with a qualified customs broker or trade counsel for binding classification and compliance decisions. This content does not constitute legal, trade compliance, or financial advice.
About the Author
Featured In These Media Publications
Did you know Career Chronicles Products have been featured in Independent Publications Career Chronicles tariff intelligence tools and content have been recognized by independent trade and procurement publications as resources for organizations navigating tariff complexity and building data-driven sourcing strategies.


A note from Ramie Virk

As the author of the Procurement and Tariff Intelligence™ newsletter and the creator of the Career Chronicles toolkits, I report on the trade policy changes that directly affect procurement, finance, and supply chain strategy. As a Procurement Leader and Tariff Risk Strategist with more than 20 years of supply chain execution experience, my work focuses on the real-world impact of trade policy on sourcing decisions, compliance exposure, and financial performance.
My expertise spans trade policy impact analysis, landed cost modeling, and tariff scenario planning, supported by hands-on experience integrating ERP systems and AI-driven automation into procurement workflows. Through The Procurement Perspective and the products, I translate Executive Orders, tariff actions, and regulatory changes into practical insights that help organizations understand how policy decisions move through supply chains and ultimately affect the bottom line.
My articles focus on procurement and tariffs to provide practical insight and strategy, not theory. I explain how these issues affect sourcing, compliance, and cost control. I also call out risky shortcuts, including practices like tariff washing that can create serious legal and financial exposure.
Example: When a company wants to buy equipment from overseas, tariffs are not a side detail because they arent’t a cost driver that can shift a project from profitable to unworkablet. A procurement expert, like me, doesn’t just focus on unit price and lead time while ignoring the complexity of the HTS codes and sourcing. I help the company find the best suppliers while fully considering these additional costs.
Procurement and tariff decisions are never just paperwork. They affect cash flow, margins, contracts, and long term strategy. My goal is to help you see the full picture before you commit to a supplier, before a shipment leaves port, and before a liquidation deadline closes your options.