
How US Tariff Rates Are Structured by Country, HS Code & Trade Program (2026 Guide)
Quick Answer: How Are U.S. Tariff Rates Structured?
U.S. tariff rates are not a single number but a layered structure built from the MFN (Most Favored Nation) base rate determined by HS code classification, modified by country of origin and trade program eligibility (USMCA, GSP, CAFTA-DR), and then overlaid with trade policy actions (Section 301, Section 232, Section 122). The effective tariff rate is the cumulative result of all applicable layers.
Understanding this layered structure is essential for procurement teams because the difference between 5% and 40%+ effective duty depends on getting all four layers right: classification, country of origin, trade program eligibility, and policy overlays. This guide explains how each layer works, how they stack, and how to calculate your true landed cost.
Who This Guide Is For
Procurement teams new to tariff classification and rate structures, supply chain leaders evaluating landed cost across different supplier countries, trade compliance officers managing HS code accuracy, finance teams trying to understand how tariff rates are calculated, and manufacturers evaluating which countries and trade programs offer the lowest duty rates.
Key Takeaways
- U.S. tariff rates are built in layers: MFN base rate + trade program adjustments + trade policy overlays (Section 301, 232, 122)
- The MFN rate is the default duty rate for WTO member countries and is determined by the product’s HTS classification at the 8-digit level
- Country of origin determines which trade programs apply — USMCA partners, GSP-eligible countries, and FTA partners may qualify for reduced or zero-duty rates
- The 10-digit HTSUS hierarchy (chapter, heading, subheading, tariff rate line, statistical suffix) determines classification precision and accuracy
- Trade policy overlays like Section 301 and Section 232 add surcharges on top of the base rate for specific countries and product categories
- The stacking effect means some products face cumulative tariff rates exceeding 40% when all layers are combined
U.S. tariff rates are structural. They are not determined by a single tariff schedule or a simple lookup. Instead, they are built through a multi-layer process where each layer adds information that modifies the duty rate. Understanding this structure is the foundational knowledge that separates reactive procurement teams from proactive ones that can model tariff exposure, negotiate supplier contracts with confidence, and identify sourcing opportunities based on tariff intelligence.
This guide explains the complete tariff rate structure as it stands in 2026. Whether you are sourcing a product for the first time, evaluating a new supplier country, or trying to model the impact of a trade policy change, this cornerstone article provides the framework you need to understand how rates are built, why they differ by country and product, and how to calculate your effective duty rate accurately.
The Layered Structure of U.S. Tariff Rates
The most important concept in tariff rate structure is this: there is no single tariff rate. Instead, there are multiple rates that apply in sequence, each one modifying or adding to the previous.
Layer 1: MFN Base Rate. Every product has a base tariff rate determined by its HTS classification. For WTO member countries with normal trade relations status, this is called the MFN (Most Favored Nation) rate. This is the starting point — typically 3% to 15% for most industrial and consumer products, though some categories (textiles, dairy, certain agricultural products) can reach 25% or higher.
Layer 2: Trade Program Adjustment. If the country of origin qualifies for a preferential trade program (USMCA, GSP, CAFTA-DR, bilateral FTAs), the rate may be reduced. Some products qualify for 0% duty under trade programs. The trade program adjustment either reduces the MFN rate or replaces it entirely with a lower special rate.
Layer 3: Trade Policy Overlays. On top of the MFN base rate (after any trade program adjustment), the government can add surcharges for specific policy reasons. Section 301 (China tariffs), Section 232 (steel and aluminum), and Section 122 (universal baseline) are the major overlays currently in effect. These add 7.5% to 25% on top of whatever rate resulted from Layers 1 and 2.
Layer 4: Effective Tariff Rate Calculation. The final effective rate is the cumulative result. If you do not account for all layers, you will systematically underestimate your actual duty exposure.

Layer 1: MFN Base Rates — The Foundation
What Is MFN and Why It Matters
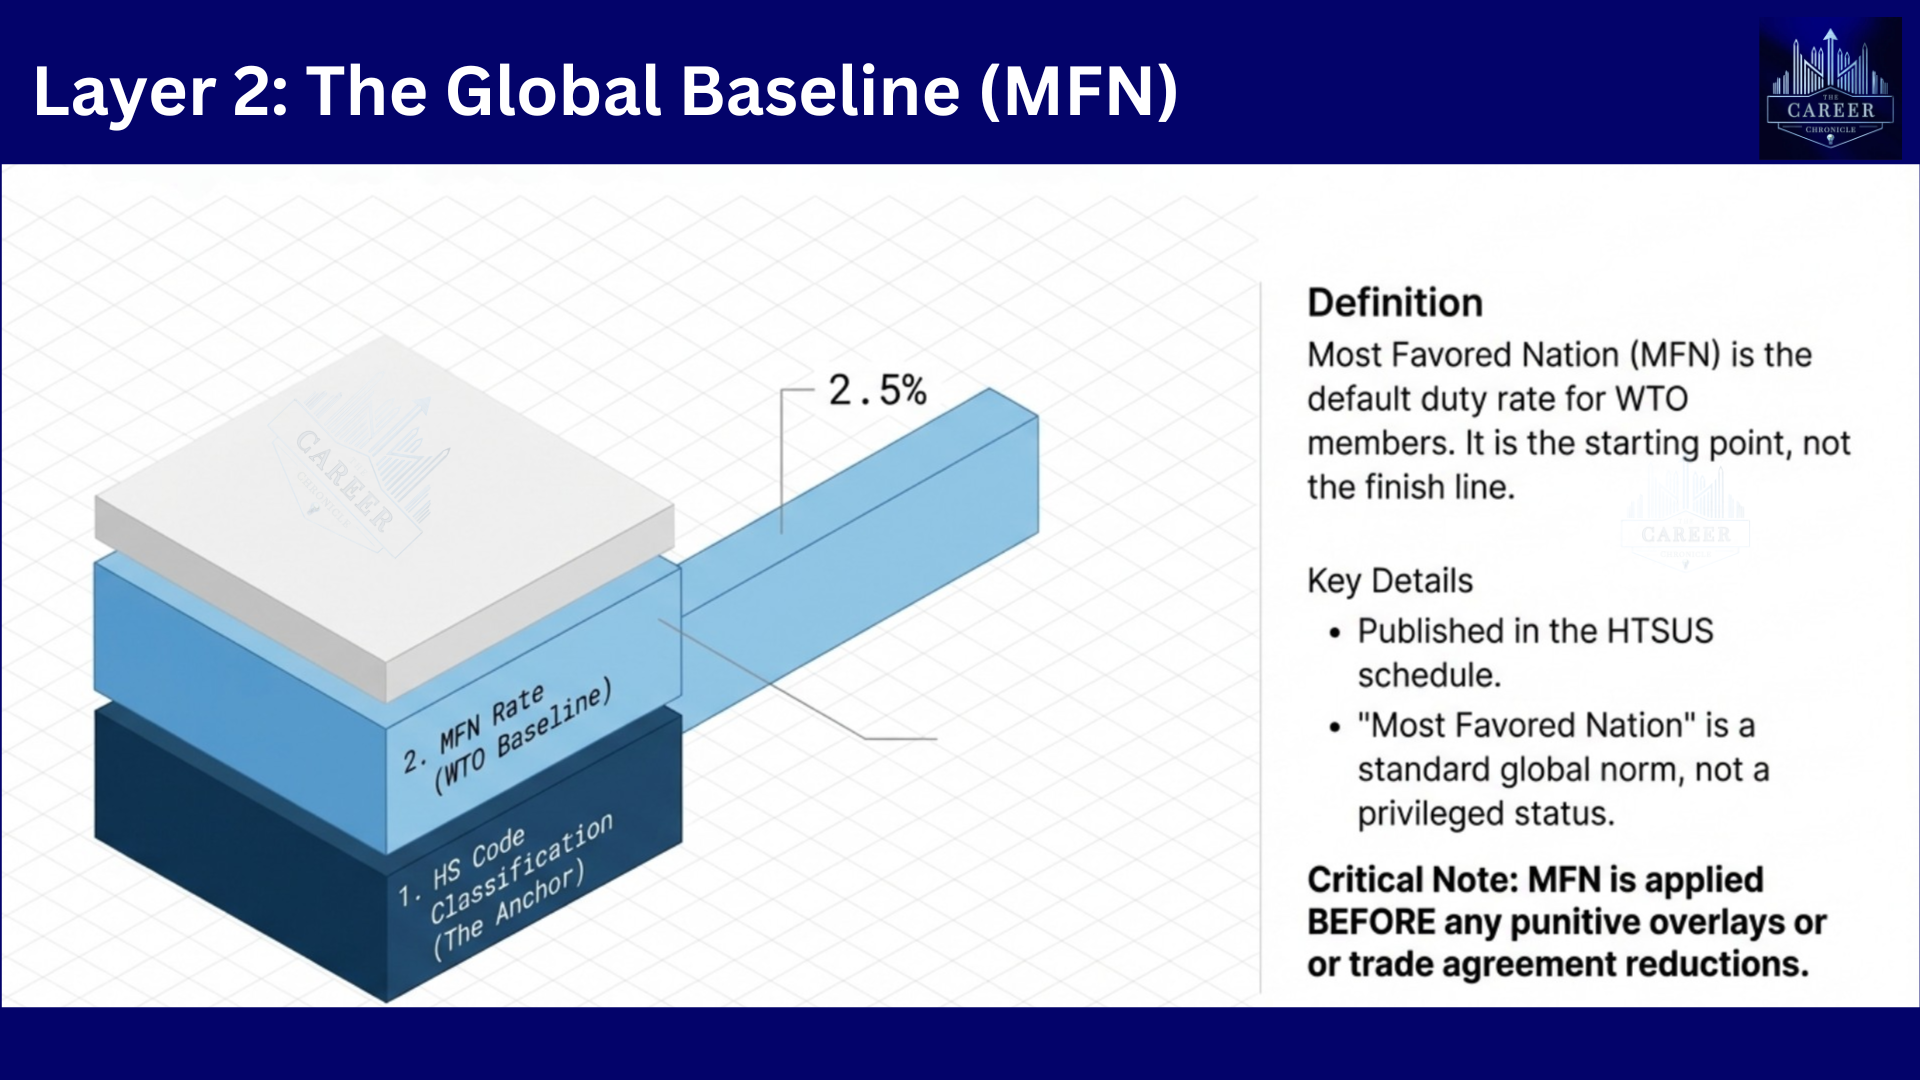
MFN stands for Most Favored Nation. It is both a trade principle and a tariff rate concept. The principle is this: if you give one WTO member country a preferential tariff rate, you must give the same rate to all other WTO members (except when they qualify for even lower rates under specific trade agreements). The rate you give the “most favored” nation is the MFN rate.
In practical terms, the MFN rate is the default rate that applies to imports from WTO member countries without specific trade agreement benefits. For the United States, this means that a product from Germany, Japan, South Korea, Mexico (outside USMCA benefits), India (outside GSP benefits), and most other countries faces the MFN rate as the starting point for duty calculation.
How MFN Rates Are Determined by HS Code
MFN rates are not determined by product type or by company preference. They are determined entirely by HTS classification. The Harmonized Tariff Schedule of the United States (HTSUS) is a 10-digit classification system that organizes all tradeable products into approximately 13,000 rate lines. Each rate line has a corresponding MFN duty rate.
The structure is hierarchical and systematic. Chapter 07 is vegetables. Chapter 10 is cereals. Chapter 39 is plastics. Chapter 73 is iron and steel. Within each chapter are headings (more specific categories), then subheadings, then individual tariff rate lines. The deeper you go into the hierarchy, the more specific the classification and the more precisely the tariff rate applies.
Why WTO Normal Trade Relations Status Matters
The United States does not grant MFN rates to all countries. Countries without WTO membership or without U.S.-granted normal trade relations (NTR) status face Column 2 rates, which are dramatically higher — often 30% to 50% or more. In practical terms, this means that for sourcing decisions, countries with NTR status (which includes nearly all trading partners) are vastly more cost-competitive than non-NTR countries.
As of 2026, the only significant U.S. trading partner without NTR status is North Korea, which is also subject to comprehensive trade sanctions. For practical procurement purposes, assume all your major supplier countries have NTR status and therefore qualify for MFN rates.
The 10-Digit HTSUS Classification System
Tariff rate classification is the bedrock of tariff calculation. If you misclassify a product — assign it to the wrong HTS code — you get the wrong tariff rate, and potentially expose yourself to CVD (customs value disagreements), penalties, and refund recovery complications. Understanding the 10-digit structure helps you avoid classification errors and know when to request a CBP Ruling for classification clarity.


Breaking Down the 10-Digit Code
The 10-digit HTSUS code is structured as follows: XX-XX-XX-XX-XX, representing Chapter-Heading-Subheading-Tariff Rate Line-Statistical Suffix.
Digits 1-2 (Chapter). The broadest category. There are 21 chapters in the HTSUS, ranging from Chapter 1 (Live animals) through Chapter 21 (Miscellaneous edible preparations). If your product is a plastic component, it falls somewhere in Chapter 39 (Plastics and articles thereof). All products in the same chapter share a general product category.
Digits 3-4 (Heading). One level deeper than chapter. Chapter 39 contains many headings: 3901 is plastic in primary forms, 3902 is polyethylene, 3903 is polyvinyl chloride, and so on. The heading tells you the general material and form.
Digits 5-6 (Subheading). More specificity. Within heading 3901 (plastic in primary forms), subheading 3901.10 is polyethylene in primary forms, 3901.20 is polypropylene in primary forms, and 3901.30 is other polyolefins. The subheading specifies the polymer type and basic characteristics.
Digits 7-8 (Tariff Rate Line). This is where you find the actual tariff rate. Within subheading 3901.10 (polyethylene), rate line 3901.10.10 might be polyethylene in pellet form, and 3901.10.50 might be polyethylene in powder form. Different rate lines within the same subheading can have different tariff rates.
Digits 9-10 (Statistical Suffix). The last two digits are used for statistical reporting purposes and do not affect the tariff rate. Both 3901.1010 and 3901.1050 are reported separately for trade statistics, but the tariff rate is determined at the 8-digit level (through the tariff rate line). For tariff rate lookup purposes, the 8-digit code is the minimum needed level of specificity.
Why Accuracy at the 8-Digit Level Is Critical
You do not need all 10 digits to find the correct tariff rate — the 8-digit code (chapter through tariff rate line) is sufficient. However, you must get those 8 digits correct. Misclassifying a product by even one digit can change the rate from 5% to 20%, or qualify it for a trade program benefit or not.
For compliance and accuracy, procurement teams should validate HS classifications for significant products through one of three methods: rely on supplier documentation and invoices (which should state HS codes), obtain a formal CBP classification ruling for new product categories, or use third-party tariff classification services that provide documented classification support.
Layer 2: Country of Origin and Trade Program Eligibility
How Country of Origin Determines Trade Program Access
The MFN base rate is the default. But many countries qualify for preferential trade programs that reduce or eliminate duties on certain products. Whether your product qualifies for the reduced rate depends entirely on country of origin.
The key question is: which country did the product originate from? For simple, single-country products, this is straightforward. A steel fastener manufactured in Mexico qualifies for USMCA benefits (if the fastener meets USMCA rules of origin). The same fastener manufactured in Vietnam does not qualify for USMCA, but may qualify for GSP benefits if Vietnam is a GSP-eligible country and the fastener meets GSP rules of origin.
Rules of origin vary by trade program. Some programs require that the product be wholly produced in the qualifying country. Others allow a certain percentage of value to come from non-member sources, as long as the product undergoes sufficient transformation in the beneficiary country. USMCA, for example, has detailed rules of origin that vary by product category — automotive parts have different rules than textiles, which have different rules than metals.
Major Trade Programs and Their Tariff Benefits
USMCA (United States-Mexico-Canada Agreement). The most comprehensive preferential trade agreement. Products that originate in Mexico or Canada and meet USMCA rules of origin typically qualify for duty rates that are lower than the MFN rate, and many qualify for 0% duty. USMCA eliminates tariffs on most goods traded between the three countries, making Mexico and Canada the lowest-cost sourcing jurisdictions for duty purposes. For steel fasteners, textiles, automotive components, and machinery, USMCA benefits are often the difference between a 12% effective rate and a 0% rate.
GSP (Generalized System of Preferences). A unilateral U.S. program that grants reduced or zero-duty rates to certain products from designated developing countries. India, Vietnam, Thailand, Indonesia, and Pakistan are major GSP-eligible countries. GSP coverage varies — some products qualify for 0% duty, others are excluded (textiles, for example, have limited GSP coverage). GSP beneficiary countries change occasionally when countries graduate out of the program due to rising incomes, so current eligibility should be verified against the official USITC list.
CAFTA-DR (Central America-Dominican Republic Free Trade Agreement). Covers Guatemala, Honduras, El Salvador, Nicaragua, Costa Rica, Panama, and the Dominican Republic. Similar to USMCA in that it provides zero or reduced duty rates for eligible products. Less comprehensive than USMCA in terms of product coverage, but significant for companies sourcing from Central America.
Other FTAs. The U.S. maintains bilateral FTAs with South Korea, Australia, Peru, Colombia, Panama, Chile, and Singapore, among others. Each provides tariff benefits for eligible products. Coverage varies, but FTA countries generally offer lower effective tariff rates than non-FTA countries at the same MFN rate.
Special Rate vs. General Rate Columns in the HTSUS
The HTSUS maintains two primary rate columns for each tariff rate line: the General rate (column 1) and the Special rate (column 2, though formatting varies). The General rate is the MFN rate that applies when no special program applies. The Special rate column lists all the trade program rates that might apply: USMCA, GSP, CAFTA, Caribbean Basin Initiative (CBI), African Growth and Opportunity Act (AGOA), etc.
The way this works in practice: a product from Mexico is classified as HTS 7318.15 (steel fasteners). The General (MFN) rate is 12%. But looking at the Special rates for 7318.15, USMCA is listed as Free (0%). So the product qualifies for 0% duty under USMCA. The same product from China at HTS 7318.15 gets the 12% MFN rate because China is not a USMCA partner. The same product from India gets the MFN rate of 12% unless it also qualifies for GSP, in which case it might get a reduced rate or even 0% depending on whether GSP covers that particular product from India.
When Country of Origin Determination Becomes Complex
Country of origin determination is typically straightforward for simple, single-country manufactured products. It becomes complex when a product is made from imported components, when assembly occurs in one country but components come from multiple countries, or when the product undergoes transformation across multiple jurisdictions.
In those cases, rules of origin require that certain percentages of value be produced in the qualifying country, or that certain processes occur in the qualifying country, or both. A steel fastener assembled in Mexico from Chinese steel plate and American equipment might not qualify for USMCA if the value-add in Mexico falls below the USMCA threshold, or if the transformation test is not met.
For complex products, obtaining a CBP ruling on rules of origin eligibility is worth the investment because misclassification or misapplication of trade program benefits can result in duty assessments and penalties if discovered during a customs audit.
Layer 3: Trade Policy Overlays — Section 301, Section 232, and Section 122
How Trade Policy Overlays Work
The MFN base rate and trade program benefits are part of the standing tariff schedule. They are relatively stable. Trade policy overlays, by contrast, are temporary or ongoing surcharges imposed by the executive branch in response to specific trade policy concerns. They stack on top of whatever rate resulted from Layers 1 and 2.
The three major overlays currently in effect are Section 301 (retaliatory tariffs on China), Section 232 (national security tariffs on steel and aluminum), and Section 122 (universal baseline tariffs). Each overlay targets different countries and products.
Section 301: Retaliatory Tariffs on Unfair Trade Practices
Section 301 of the Trade Act of 1974 gives the USTR authority to impose tariffs on countries found to engage in unfair trade practices or intellectual property violations. The primary Section 301 action is the four tariff lists on China, which impose duties of 7.5% to 25% on approximately $370 billion in Chinese imports.
Section 301 is layered on top of the MFN rate. A product with a 6% MFN rate from China and a 25% Section 301 overlay faces a 31% effective rate. If the product also faces Section 122 or Section 232, the layers accumulate further. The stacking of Section 301 on top of MFN creates the highest effective rates that most procurement teams encounter.

Section 232: National Security Tariffs on Steel and Aluminum
Section 232 of the Trade Expansion Act of 1962 authorizes the President to impose tariffs on products deemed strategically important to national defense. The current Section 232 action imposes a 25% tariff on steel imports and a 10% tariff on aluminum imports from most countries (with some exemptions for USMCA partners and a few others).
Section 232 applies to raw materials and products that contain significant steel or aluminum content. If you are sourcing a steel forging, a steel fastener, an aluminum extrusion, or a composite product with a high steel or aluminum content, Section 232 likely applies. It stacks on top of the MFN rate, creating cumulative duties that can reach 40% or more for some steel products.

Section 122: Universal Baseline Tariffs
Section 122 of the Trade Act of 1974 establishes baseline tariffs on certain product categories deemed important to domestic manufacturing. Current Section 122 actions target specific products (machinery, chemicals, minerals) and add surcharges of 5% to 15% on top of the MFN rate. Section 122 is less widely applicable than Section 301 or Section 232, but for affected product categories, it represents a permanent tariff surcharge.

Country Exemptions and Program-Specific Carve-Outs
Not all overlays apply to all countries equally. USMCA partners (Mexico and Canada) are exempted from Section 232 steel tariffs. Some countries have negotiated exemptions from Section 301. Australia and Japan negotiated deals that reduced or eliminated Section 232 exposure. Understanding country-specific exemptions is essential because the same product from two different countries can have dramatically different effective rates.
The Tariff Stacking Effect — How Cumulative Rates Are Calculated
A Real-World Worked Example: Steel Fastener HTS 7318.15
Let’s follow a single product through the tariff rate calculation to show how layers accumulate.
Product: Carbon steel fasteners, HTS 7318.15
Base MFN Rate: 8%
Now let’s calculate the effective rate for the same product from different countries:
| Country | MFN Base | Trade Program | Section 301 | Section 232 | Effective Rate |
|---|---|---|---|---|---|
| Mexico (USMCA) | 8% | Free (0%) | N/A | N/A (exempt) | 0% |
| India (GSP) | 8% | Free (0%) | N/A | 25% steel | 25% |
| Vietnam | 8% | No program | N/A | 25% steel | 33% |
| China | 8% | No program | 25% (List 3) | 25% steel | 58% |
| EU/Germany | 8% | No program | N/A | 25% steel | 33% |
The same product faces a 0% effective rate from Mexico (USMCA partner), but a 58% effective rate from China (MFN + Section 301 + Section 232). This is the tariff stacking effect in action, and it is why country of origin sourcing decisions are fundamentally tariff-driven in many procurement categories.
How to Calculate Cumulative Rates
The formula is straightforward once you have all the layers identified. Tariff rates do not multiply — they add. If you have an 8% MFN rate, a 25% Section 301 overlay, and a 25% Section 232 overlay, the effective rate is 8% + 25% + 25% = 58%.
This is where many organizations make errors. They look at a product and see a 8% base rate and think the tariff exposure is low, when in fact the product faces significant overlays that double or triple the effective rate.
The formula is: Effective Rate = (Declared Value × MFN Rate) + (Declared Value × Trade Program Adjustment) + (Declared Value × Overlay 1) + (Declared Value × Overlay 2)… For simplicity in most procurement planning, add the percentage rates and multiply by the product value: Effective Duty = Product Value × (MFN Rate + Overlays).
How Procurement Teams Use Tariff Rate Intelligence
Understanding the tariff rate structure is not an academic exercise. It directly informs sourcing decisions, supplier selection, contract negotiations, and financial forecasting.
Sourcing Country Evaluation
When evaluating suppliers in different countries, tariff rate structure becomes a primary cost variable. A supplier in Vietnam might quote a 10% lower FOB price than a Mexico-based supplier, but if the Vietnam product faces a 33% effective tariff and the Mexico product faces a 0% tariff, the Mexico supplier is actually cheaper on landed cost. Tariff rate intelligence converts raw FOB prices into apples-to-apples landed cost comparisons.
Supplier Contract Negotiation
When you understand the tariff structure, you can negotiate supplier contracts with more precision. A Mexico supplier knows that the product qualifies for 0% USMCA duty. A China supplier knows that products face 25% to 58% effective rates depending on product and overlays. You can use this knowledge to negotiate pricing, to structure cost-sharing arrangements, or to negotiate pass-through tariff clauses that adjust pricing automatically if tariff rates change.
Trade Program Optimization
Many organizations leave tariff benefits on the table because they have not optimized their sourcing around trade program eligibility. If you source from multiple countries, ensuring that your USMCA products actually qualify for USMCA treatment, that your GSP products are classified correctly to trigger GSP rates, and that you are not missing FTA opportunities in other jurisdictions, can mean 5% to 25% in tariff savings across the portfolio.
Landed Cost Modeling and Financial Forecasting
Finance teams that model tariff impact at the SKU level produce more accurate cost forecasts than teams that estimate tariff as a portfolio percentage. Because tariff rates vary so dramatically by country, product, and policy environment, accurate modeling requires building tariff exposure by product classification, country of origin, and applicable overlays. Organizations that do this well have a clear advantage in pricing accuracy and margin forecasting.
Look Up Your Tariff Rate — Free Tool
Need to verify the Section 301 status and effective tariff rate for a specific HS code? Use the Live U.S. Tariff Rate Lookup — free, no account required.
Covers MFN base rates, Section 301 (all four lists), Section 232, Section 122, USMCA, and more. 60+ countries, 905 tariff rate lines, 9 trade programs. Updated March 2026.

Structured Response Strategies for Section 301 Tariff Exposure
Organizations managing Section 301 tariff exposure have five primary response strategies. The optimal approach depends on product category, supplier concentration, contract terms, and the organization’s risk tolerance.
1. Supplier Diversification and Country-of-Origin Shifting
Moving procurement volume from China to non-Section 301 countries reduces tariff exposure directly. Common alternative sourcing destinations include Vietnam, India, Thailand, Mexico (under USMCA), and Taiwan. However, supplier qualification timelines, quality control requirements, and logistics costs must be factored into the total cost analysis. A 25% tariff savings means nothing if the alternative supplier adds 20% in quality defects and 8% in freight.
2. Tariff Engineering Through HS Reclassification
Some products may qualify for an alternative HTS classification that carries a lower base rate or falls outside Section 301 coverage. Tariff engineering involves reviewing product specifications, manufacturing processes, and component materials to determine if a different classification is legally defensible. This strategy requires trade compliance expertise and should be validated through a CBP ruling to avoid classification disputes.
3. Trade Program Optimization
Products sourced from countries with preferential trade agreements (USMCA, CAFTA-DR, GSP-eligible countries) may qualify for reduced or zero-duty treatment. Organizations that have not evaluated trade program eligibility across their full procurement portfolio may be paying higher effective rates than necessary — not because of Section 301, but because they have not optimized the base rate layer.
4. Contract Renegotiation with Cost-Sharing Provisions
Tariff cost allocation is a contract negotiation issue. Some organizations absorb the full tariff burden internally. Others negotiate tariff pass-through provisions, cost-sharing arrangements, or tariff escalation clauses that adjust pricing automatically when tariff rates change. The key is having accurate tariff cost data to support the negotiation — simulation tools that model duty exposure at the SKU level provide the evidence base for these conversations.
5. Refund Recovery for Overpaid Duties
Organizations that paid Section 301 tariffs during exclusion-eligible periods, that have HS classification errors, or that qualify for retroactive trade program benefits may be eligible to recover overpaid duties through CBP protest and Prior Disclosure procedures. The recovery window is time-limited and tied to CBP liquidation schedules, so this strategy requires timely action.


